
Rising temperatures, severe flooding, intense hurricanes, bitterly cold winters, droughts and destructive wildfires seem to be happening more frequently.
Even most former climate change skeptics now acknowledge that the world is warming. The hottest year on record was 2024, followed by 2023.
Sea levels are rising because of melting polar ice sheets, and the frequency and severity of destructive weather continue to increase. In the past 50 years, the number of natural disasters worldwide has risen more than 450%.
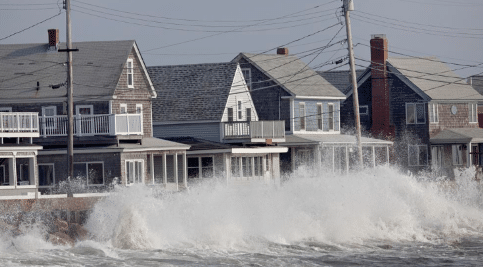
The rising sea level is affecting coastal areas all over the world. When the sea level rises, it’s not just those below the new high tide line who have to worry. Rising seas mean more potential floods. Tidal flooding and storm surges become even more likely for low-lying coastal areas.
Climate volatility and your home
Many factors can affect your homeowners insurance rates, including weather patterns where you live.
Your insurer considers the odds of your property sustaining damage when calculating your premium. Climate change means those odds are getting worse.
Higher premiums
Because of increasingly severe weather, insurance companies incur more losses. They then pass those losses down to policyholders in the form of higher premiums. In the case of rising sea levels, homeowners in flood-prone areas face rising flood insurance premiums.
And in wildfire-prone areas, it may be difficult to get insurance at all.
Insurance providers in Canada are watching carefully and adapting as needed. They are starting to:
- Forecast weather more accurately, analyzing risks down to specific regions
- Implement larger deductibles and fewer coverage options in high-risk areas
- Apply separate deductibles on some policies in areas prone to hurricanes, tornadoes, and wind and hail damage
Financial incentives for climate resilience
The insurance industry may someday offer incentives to homeowners who take steps to make their properties more climate-resilient. These may include lower deductibles and more favorable premiums. For example, green homes could receive discounted rates.
The concept is similar to safe drivers receiving discounts because they are less likely to be involved in accidents that lead to insurance claims.
Customers who generate solar power, wind power or geothermal energy can already reap the benefits of the discounted premiums some insurers offer.
Protect yourself from extreme weather losses
The best thing you can do to protect yourself from extreme weather losses and rising homeowners insurance costs is to avoid purchasing any of the following:
- Coastal property
- Property that lies in a flood zone
- Property in an area with frequent tornadoes, hailstorms or windstorms
- Property in a wildfire-prone region
Of course, your home may fall into one of these categories. If it’s susceptible to weather-related damage, consider renovations that make it more resilient.
Here are some other things to keep in mind:
- Do you live in a high-risk flood zone? If so, you may want to opt for flood insurance.
- Does your policy cover “actual cash value coverage” or “replacement cost coverage”? Actual cash value accounts for depreciation when reimbursing you for losses. Replacement value covers the full cost of replacing your damaged items. It runs about 10% more on average.
- What are the caps and limitations on your coverage? The age of your roof may affect how much you’ll get toward replacing it, or your screened-in patio may not be covered.
Know that earthquake and flood insurance are not normally included in standard homeowners policies. You need to purchase those coverages separately.
If you haven’t completed a home inventory yet, do it now, before a catastrophic weather event. Having a list and video or photo proof of the things you own will help you get reimbursed if your house is damaged.
Review your coverage needs
You may not be able to completely avoid weather-related damage from a changing climate. But taking precautions and knowing exactly how you’re covered can help if disaster strikes. Contact us to discuss your insurance needs.
